What happens to your home and mortgage when you separate?
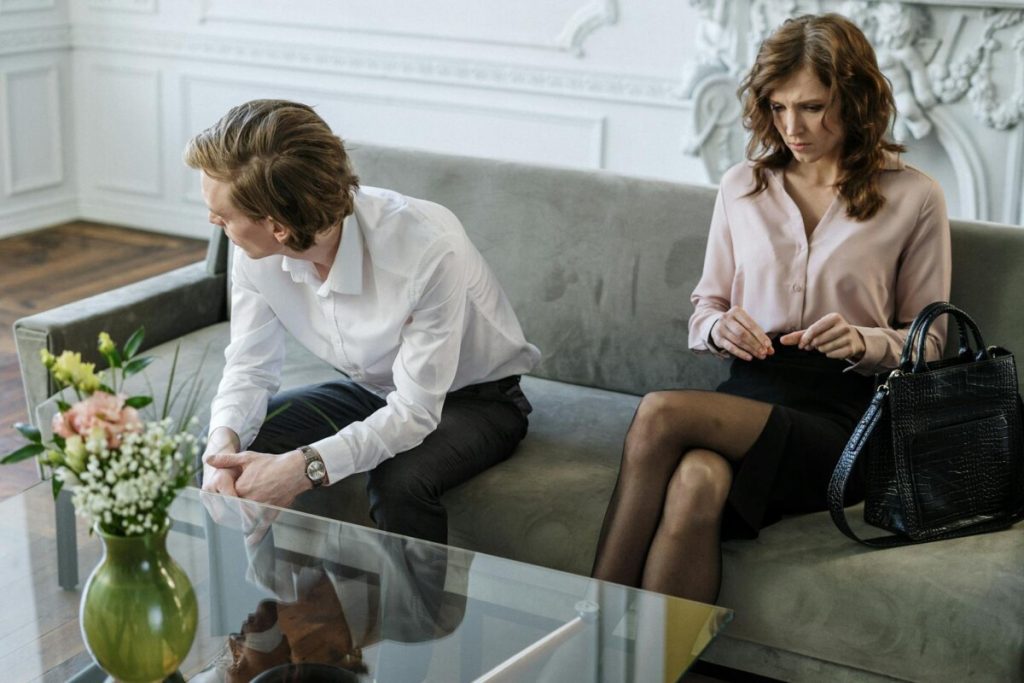
Separation brings emotional strain, but the practical questions can feel just as heavy, especially when your home and mortgage sit at the centre of it all. You might worry about where you will live and whether you can afford the payments alone.
While it’s important to seek advice from divorce solicitors to understand your position, it also helps to be familiar with UK law around ownership and mortgages.
Who owns the home?
If you both own the property, check the title register to see whether you hold it as joint tenants or tenants in common. Joint tenants usually share the home equally, while tenants in common own defined shares, such as 60/40, which often reflect different contributions. For example, if you paid the deposit from savings before you moved in together, a tenants-in-common arrangement may recognise that input.
If the home sits in one name only, ownership looks simpler, but it does not always end the conversation. You may still have a claim if you contributed to the purchase price, renovations or mortgage and you can gather bank statements or receipts to show that link.
What happens to the joint mortgage after separation?
A joint mortgage does not split just because you separate. The lender expects the full monthly payment and you both remain responsible until you change the agreement.
If one of you moves out, missed payments still affect both credit files, which can block future borrowing for years. A practical approach involves setting up a temporary payment plan that covers the mortgage while you negotiate longer-term options.
Should you sell, keep or transfer the property?
Selling the home clears the mortgage and releases equity that you can divide, which often gives both of you a clean break and cash for new deposits. Keeping the property can work if one of you can afford the payments alone and buy out the other’s share. In this situation, a transfer of equity removes one name from the deeds, but the lender must approve the affordability.
If neither option fits immediately, you can agree to keep the property for a fixed period, such as until children finish school, while you share costs and future sale proceeds. Remember, you can speak to a broker to test affordability before you commit.
How does your relationship status affect decisions?
Marriage or civil partnership brings wider legal discretion, as courts can adjust property interests to meet needs, especially where children rely on stability. Cohabiting couples do not have the same automatic rights, so outcomes depend more heavily on ownership records and evidence of contributions.